
Bad Credit Is Costing You More Than You Think
The best credit repair experts can make a real difference if errors on your credit report are holding you back from loans, fair interest rates, or even a place to rent.
Professional services offer various levels of support, from comprehensive dispute plans and legal expertise to advanced technology and affordable monthly options. Most reputable companies provide a money-back guarantee to ensure you feel confident in their ability to deliver results.
More than a quarter of people who check their credit reports find errors serious enough to hurt their score, according to a Consumer Reports study. That means millions of people are paying higher interest rates — or getting denied entirely — because of mistakes they didn’t even make.
If you’ve been turned down for a mortgage, a car loan, or a credit card, the problem might not be your financial habits. It could be bad data sitting in your credit file right now.
That’s exactly where credit repair experts come in.
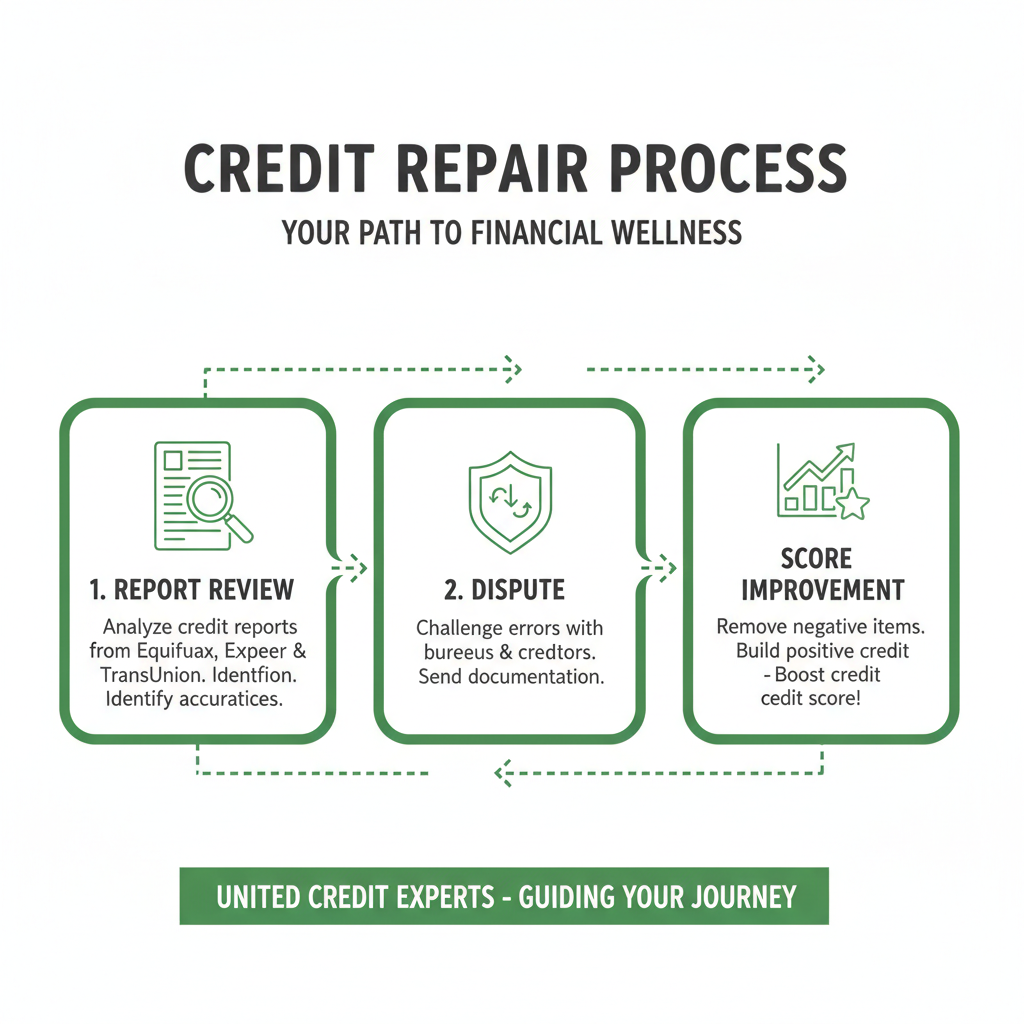
Professional credit repair services review your reports line by line, identify inaccuracies, and dispute them with the three major credit bureaus — Equifax, Experian, and TransUnion — on your behalf. Some also send creditor intervention letters and provide legal support to push harder on stubborn items.
How the Best Credit Repair Experts Evaluate Your Reports
When you decide to work with a professional, the process doesn’t just start with a “shotgun” approach of disputing everything. The best credit repair experts begin with a deep dive. They look at your credit history through a magnifying glass to find the “why” behind a low score.
In our experience at United Credit Experts, we’ve seen how overwhelming a credit report can look. It’s essentially a giant list of your financial history—money you’ve borrowed and how you’ve paid it back. But because humans and computers handle this data, mistakes happen constantly.
A true expert performs a line-by-line review. They aren’t just looking for big things like a bankruptcy that isn’t yours; they are looking for “micro-errors.” This includes:
- Typos in your name or address that link you to someone else’s bad debt.
- Duplicate accounts that make it look like you owe twice as much as you do.
- “Zombie” debts that are too old to be reported but keep popping up.
- Accounts where you were only an authorized user but are being held responsible as the primary owner.
According to a Consumer Reports study on credit report errors, 27% of participants found errors serious enough to impact their scores. This is why understanding the ABCs of Credit is so vital. If you don’t know what should be there, you won’t know what’s wrong.
The legal backbone of this entire industry is the Fair Credit Reporting Act (FCRA). This federal law gives you the right to an accurate credit report. If something is inaccurate, unverifiable, or outdated, the credit bureaus are legally required to fix it or remove it. The best credit repair experts use this law to craft formal dispute letters that demand the bureaus do their jobs.
Attorney-Backed Support from Best Credit Repair Experts
Sometimes, a simple letter to a credit bureau isn’t enough. Some creditors are stubborn, and some debt collectors are, shall we say, “persistent” even when they are wrong. This is where attorney-backed support becomes a game-changer.
Leading services use licensed attorneys and paralegals to handle the heavy lifting. Having a legal professional on your side means they can engage in “creditor intervention.” Instead of just asking the bureau to check their notes, an attorney can send a letter directly to the creditor, demanding proof that the debt is valid and reported correctly.
When you know your rights under the FCRA, you realize that you have a lot of power. If a company continues to report “lies” on your credit report after being told they are wrong, there is litigation potential. While most credit repair doesn’t end up in a courtroom, the threat of legal action from a law firm often makes creditors much more cooperative.
Strategic Dispute Waves and Factual Methodology
Credit repair isn’t a one-and-done event. It’s more like a series of waves. The best credit repair experts use a strategic approach rather than sending one angry letter and giving up.
This often involves “Metro 2” compliance. Metro 2 is the standard language that creditors use to report data to bureaus. If the data isn’t reported in the exact right format, it can be challenged. Experts look for these technicalities to ensure your report is 100% compliant with federal standards.
The process usually works in cycles:
- The First Wave: Challenging the most obvious errors and requesting verification for questionable items.
- The Response: The bureaus have 30 days to investigate. They will either verify the item, correct it, or delete it.
- The Follow-Up: If a bureau claims an item is “verified” but doesn’t provide proof, the experts send a second, more specific challenge letter.
This persistent back-and-forth is what eventually leads to the removal of unverifiable negative items that are dragging down your score.
Key Features to Look for in Professional Services
If you’re looking for the best credit repair experts, you shouldn’t just pick the first name you see on a billboard. You want a partner that offers more than just “letter writing.”
A top-tier service should provide a secure client dashboard. You should be able to log in at 2 AM and see exactly which items are being disputed and what the status is. Transparency is everything in this business.
Here is a list of essential service features to look for:
- Credit Monitoring: You need to see changes in real-time. Many experts include this so you don’t have to pay for a separate service.
- Identity Theft Protection: If your credit was ruined by fraud, you need insurance and monitoring to make sure it doesn’t happen again.
- Cease and Desist Letters: If debt collectors are harrassing you, your credit repair team can send letters to stop the phone calls.
- Goodwill Requests: For those times when you actually did make a mistake (like one late payment on an otherwise perfect account), an expert can send a “goodwill” letter asking the creditor to remove the mark as a courtesy.
Personalized Action Plans for Mortgage Readiness
For many of our neighbors in Northwest Indiana and Crown Point, the goal of credit repair isn’t just a higher number—it’s a set of keys to a new home. Getting “mortgage-ready” is a specific process.
Lenders don’t just look at your score; they look at your debt-to-income ratio and the “story” your credit report tells. If you have a bunch of open collections, even with a decent score, a mortgage lender might say no.
Understanding what affects a credit score is the first step. The best credit repair experts will sit down with you and create a personalized action plan. This might include:
- Targeting specific high-impact items: Removing a recent collection can do more for your score than removing an old “paid” late payment.
- Balance Management: Coaching you on how to pay down credit cards to stay under 30% utilization.
- Financial Coaching: Helping you understand how to build new positive credit while the old negative stuff is being removed.
Transparent Pricing and Money-Back Guarantees
Let’s talk about the “elephant in the room”—the cost. Credit repair isn’t free, but it should be transparent. Federal law, specifically the Credit Repair Organizations Act (CROA), strictly forbids companies from charging you before they have performed the work.
Most companies use a “pay-as-you-go” model. You might pay a “first-work fee” or “setup fee” after the initial analysis is complete, followed by a monthly subscription.
Common Fee Structures:
- Setup Fees: Usually range from $19 to $195.
- Monthly Fees: Usually range from $49 to $149 depending on the level of service.
- Per-Deletion Fees: Some companies only charge you when an item is actually removed (though this is less common now).
A huge red flag is a company that doesn’t offer a guarantee. The best credit repair experts often offer a 90-day money-back guarantee. If they can’t get anything removed or corrected within the first 90 days, you get your money back. This shows they have “skin in the game.”
Costs, Timelines, and the DIY Alternative
You might be wondering, “Can’t I just do this myself?” The answer is yes. Technically, anything a credit repair company does, you can do for free. But there is a trade-off between money and time.
| Feature | Professional Service | DIY Repair |
|---|---|---|
| Cost | $50–$150 per month | $0 (Free) |
| Effort | Low (they do the work) | High (you write/mail letters) |
| Expertise | High (know legal loopholes) | Low (learning as you go) |
| Success Rate | Generally higher for complex cases | Good for simple errors |
| Timeline | 4–6 months on average | 6–12 months on average |
If you want to go the DIY route, start by visiting annualcreditreport.com. This is the only site authorized by federal law to give you a free credit report from all three bureaus every week.
You can also find how to repair your credit for free on the Consumer Financial Protection Bureau (CFPB) website. They even provide templates for dispute letters.
However, many people find that after the first round of “verified” responses from the bureaus, they don’t know how to follow up. That’s why hiring the best credit repair experts is often worth the investment—they have the systems in place to keep the pressure on until the job is done.
Frequently Asked Questions about Credit Repair Experts
Credit repair can feel like a “black box” where you aren’t sure what’s happening inside. We believe in simplifying credit basics so you feel empowered, not confused. Here are the most common questions we hear.
Can the best credit repair experts remove accurate negative items?
This is a big one. No. If you missed a payment last month and the bank reported it correctly, no legitimate credit repair company can “erase” that. It is a “legitimate negative.”
Most negative items stay on your report for seven years. Bankruptcies can stay for up to ten years. However, if that negative item is missing a piece of information—like the date of the last activity—it becomes “unverifiable.” Under the law, if it can’t be 100% verified, it must be removed. This is the “legal loophole” that experts use to help you.
How long does it take to see results from professional repair?
Credit repair is a marathon, not a sprint. Because the credit bureaus have 30 days to respond to any dispute, and it takes time for mail to travel and systems to update, you should expect a 45-day cycle for each “wave” of disputes.
Most clients start seeing initial improvements within 60 days. However, to see a significant “transformation” of a credit report with multiple errors, it usually takes 4 to 6 months. Beware of anyone promising a 700 score in 30 days—that’s just not how the system works.
What are the red flags of a credit repair scam?
The credit repair industry has some “bad actors,” so you need to be careful. Here are the warning signs:
- Upfront Payments: If they ask for the full fee before doing any work, run. It’s illegal.
- “New Identity” Promises: If they tell you to apply for an Employer Identification Number (EIN) to start a “new” credit file, that is federal fraud.
- Guaranteed Score Increases: No one can guarantee a specific number because the bureaus are independent.
- Lack of Written Contracts: You have a legal right to a written contract and a 3-day window to cancel without any penalty.
Conclusion
At the end of the day, credit repair is about more than just numbers on a screen; it’s about your future. Whether you want to buy a home in Crown Point, get a better car loan in Northwest Indiana, or just stop worrying about your financial “reputation,” the best credit repair experts can provide the guidance you need.
At United Credit Experts, we believe in simplifying the complex. Credit is just “lent money” that you promise to pay back later. When the record of that promise gets messy because of errors or identity theft, you have the legal right to fight back.
Don’t let bad data dictate your life. Whether you choose to use professional help or tackle it yourself, the most important step is to start. Get started with professional credit consulting today and take back control of your financial health. Your future self will thank you!