
Your Credit Score Is Holding You Back — Here’s How to Fix It
If you’re looking for the best local credit repair, here’s a quick overview of what to look for and how it works:
Top qualities of the best local credit repair services:
- Transparent pricing — no large upfront fees before work begins
- CROA compliance — legally required to deliver services before charging
- Dispute expertise — files challenges with all three major bureaus (Equifax, Experian, TransUnion)
- Local knowledge — understands your state’s specific credit laws and regulations
- Proven results — verifiable client outcomes, BBB accreditation, and real reviews
- Money-back guarantee — reputable companies stand behind their work (typically 90 days)
- Clear timeline — most clients see initial results within 45–60 days
Your credit score touches almost every corner of your financial life. It affects whether you get approved for a mortgage, what interest rate you pay on a car loan, and sometimes even whether you can rent an apartment.
And here’s what makes it worse: many people are being held back by errors they don’t even know exist.
According to a Consumer Reports investigation, more than one-third of consumers found mistakes on their credit reports. A Federal Trade Commission study found that 5% of consumers had errors serious enough to affect the rates they were offered on loans and insurance. That’s millions of people paying more than they should — or getting denied entirely — for something that isn’t even their fault.
The good news? Those errors can be disputed and removed. That’s exactly what credit repair is for.
But not all credit repair help is equal. A national call center doesn’t know your local housing market, your state’s consumer protection laws, or the specific creditors in your area. A local credit repair service does — and that difference can matter a lot when you’re trying to get approved for a home or a car loan as quickly as possible.
Why Choosing the Best Local Credit Repair Service Matters
When you’re dealing with something as personal as your financial future, having a local partner makes a world of difference. We often see consumers get lost in the shuffle of giant national firms where they are just a number in a database. In Northwest Indiana and Crown Point, we believe in a more hands-on approach.
For better or worse, your our credit history is enormously important. Not only is it used to determine your eligibility for personal loans, mortgages, car loans, student loans, and other types of borrowing, but it’s also sometimes used to determine your eligibility for a job, an apartment rental, a … It can even affect your dating life! But beyond the social implications, the financial weight is heavy.
Choosing the best local credit repair means you get:
- Personalized Attention: You aren’t calling a 1-800 number and talking to a different person every time. Local experts understand the specific challenges facing residents in Indiana.
- Local Market Expertise: If you’re trying to buy a home in Crown Point, a local service knows the lenders and the specific requirements they look for. They can help tailor your credit improvement strategy to meet those local mortgage standards.
- Face-to-Face Consultations: There is a level of trust that comes from being able to sit down with someone and go over your credit report line by line.
- State-Specific Regulations: Indiana has its own set of consumer protection laws. A local company is well-versed in these nuances, ensuring your rights are protected under both federal and state guidelines.
- Community Reputation: Local businesses live and die by their reputation in the community. You can check local reviews and ask your neighbors about their experiences.
At United Credit Experts, we like to keep things simple. We define credit as “money that is lent to you now with the understanding that you will pay it back later.” When that trust is damaged by errors or old negative items, it’s our job to help you restore it. Understanding What Affects a Credit Score is the first step in taking back control.
How Professional Credit Repair Works to Boost Your Score
Many people ask us, “How do you actually ‘repair’ credit?” It’s not magic; it’s a systematic process of holding credit bureaus and creditors accountable for the information they report about you.

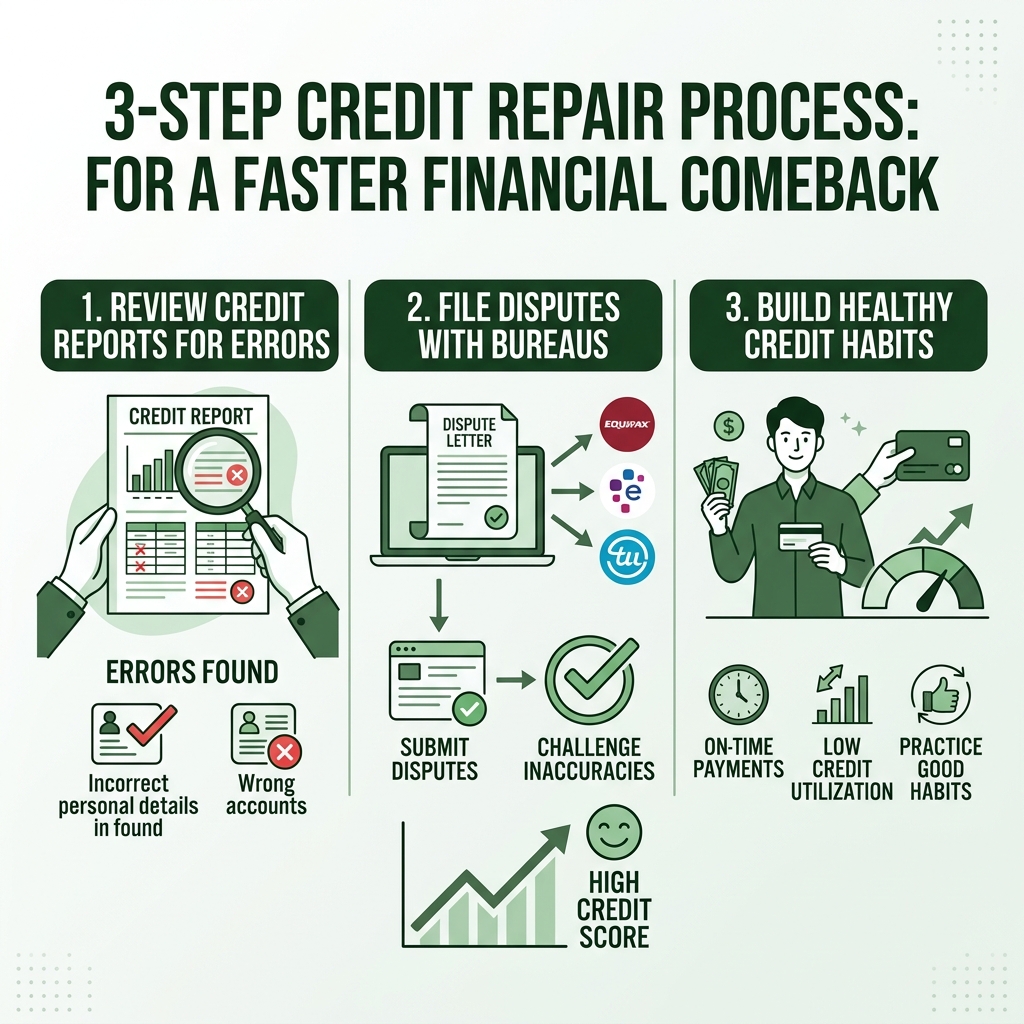
The process typically follows these steps:
- The Deep Dive: We pull your reports from all three major bureaus—Equifax, Experian, and TransUnion. We look for everything from simple typos in your name to complex errors like accounts that don’t belong to you or debts that are past the legal reporting limit.
- Identifying Inaccuracies: According to a Consumer Reports investigation Unfortunately, mistakes on credit reports happen way too often.According to a Consumer Reports investigation, one-third of volunteers who participated in the project found mistakes in their reports when they checked. You can attempt to correct inaccuracies in your credit report without hiring a serv… These mistakes are more common than most people realize.
- Filing Disputes: Once an error is found, a formal dispute is filed. Under the Fair Credit Reporting Act (FCRA), credit bureaus generally have 30 days to investigate your claim. If they can’t verify the information is 100% accurate and timely, they must remove it.
- Creditor Negotiations: Sometimes, the issue is with the original creditor or a collection agency. Professional services can communicate directly with them to resolve discrepancies or negotiate “pay-for-delete” agreements where applicable.
- Score Optimization: It’s not just about removing the bad; it’s about building the good. This involves strategies like lowering your credit utilization ratio (how much of your available credit you’re using) and ensuring you have the right mix of credit accounts.
It is vital to Know Your Rights FCRA. You have the legal right to an accurate, fair, and substantiated credit profile. Professional credit repair ensures that these rights aren’t just words on a page, but a reality for your financial life.
Evaluating Top Local Credit Repair Providers
Finding the best local credit repair in Northwest Indiana requires a bit of detective work. You want a partner who is transparent, ethical, and effective. We recommend a thorough vetting process before signing any contracts.
Start by checking for BBB (Better Business Bureau) accreditation. While not the only factor, it shows a commitment to resolving consumer complaints. You should also utilize the Consumer Complaint Database to see if a company has a history of predatory or fraudulent practices.
When evaluating a provider, look for:
- Client Testimonials: Real stories from people in your area who have seen measurable results.
- Transparency: They should be able to explain exactly what they do and how they charge.
- Education Focus: A good company doesn’t just “fix” your credit; they teach you how to maintain it. Learning the ABCs of Credit is essential for long-term success.
Key Factors to Consider for the Best Local Credit Repair
Not all service plans are built the same. When comparing the best local credit repair options, pay close attention to the following:
- Service Tiers: Does the company offer different levels of service based on your needs? Someone with one or two errors might not need the same aggressive package as someone dealing with identity theft or multiple collections.
- Monthly Subscriptions vs. Flat Fees: Most reputable companies charge a monthly fee. Be wary of anyone asking for a massive flat fee upfront before any work is done.
- Initial Setup Fees: There is often a “first-work” fee to cover the initial analysis and setup of your file. This is standard, but it should be reasonable.
- Satisfaction Guarantees: Look for a 90-day money-back guarantee. This shows the company is confident in their ability to get results.
- Attorney-Backed Support: Some firms have licensed attorneys on staff to handle complex legal disputes, which can be a significant advantage.
Understanding how the Category: Credit Bureaus operate is key to knowing why these factors matter. The bureaus are large, automated machines; sometimes you need a professional to know which buttons to push to get a human response.
Understanding Costs, Timelines, and Legal Protections
Let’s talk numbers and time. We know you want your credit fixed yesterday, but legitimate credit repair is a process, not a “quick fix.”
The Cost: Typically, you can expect to pay an initial setup fee ranging from $79 to $195, followed by monthly subscription fees between $50 and $150. Some companies offer discounts for couples or military members. Under the Credit Repair Organizations Act (CROA), companies are prohibited from charging you before they have performed the services they promised.
The Timeline:
- 30 Days: The standard window for bureaus to investigate a dispute.
- 45–60 Days: When most clients start seeing their first round of results and score increases.
- 4–6 Months: The average time most people stay with a service to see meaningful, long-term improvement.
- 7–10 Years: How long negative items like bankruptcies or late payments normally stay on your report if you take no action.
The Results: While no one can guarantee a specific score, past data shows that many consumers see an average increase of 40 points in just four months, with some seeing jumps of 100 points or more over time.
Our Process is designed to be transparent so you know exactly what is happening at every stage of your journey.
Avoiding Scams While Searching for the Best Local Credit Repair
Unfortunately, the credit repair industry has its share of “bad actors.” Protecting yourself means knowing the red flags.
- Upfront Payment: If they demand full payment before they’ve done anything, walk away. It’s illegal.
- Guaranteed Point Increases: No one can guarantee your score will go up by exactly 100 points. Credit scores are calculated using complex algorithms that no third party controls.
- Identity Substitution: If a company suggests you create a “new” credit identity using an EIN (Employer Identification Number) instead of your Social Security number, run. This is a federal crime.
- Asking You to Lie: Never work with a company that suggests you dispute information that you know is accurate and timely.
- No Written Contract: You are legally entitled to a written contract that outlines your rights and the services to be performed.
Educating yourself through the Category: Credit Scores resources can help you spot these scams from a mile away.
DIY vs. Professional Help for the Best Local Credit Repair
Can you fix your credit yourself? Absolutely. You have the legal right to dispute errors for free by contacting the bureaus directly.
DIY Credit Repair:
- Pros: It’s free (aside from postage and time). You have total control.
- Cons: It is incredibly time-consuming. You have to learn the legal language of the FCRA. Bureaus often send “automated” rejections that can be frustrating to overcome.
Professional Credit Repair:
- Pros: Saves you hundreds of hours of work. Professionals know the “tricks of the trade” and how to respond to bureau stalls. They often have proprietary software to track and manage multiple disputes.
- Cons: It costs money. You have to vet the company to ensure they are reputable.
If you have a complex situation—like a mix of collections, late payments, and identity theft—hiring a professional is often the most efficient path to a faster financial comeback. Check out our FAQs to help decide which path is right for you.
Frequently Asked Questions about Local Credit Repair
How long does the credit repair process usually take?
While every situation is unique, most of our clients in Northwest Indiana see initial results within 45 to 60 days. For a comprehensive cleanup that addresses multiple negative items and focuses on score optimization, the average timeframe is about four to six months. More complex cases involving legal disputes or identity theft can take up to a year.
What are the specific state regulations for credit services?
In Indiana, credit services organizations must follow both federal laws (like CROA and FCRA) and state-specific protections. These laws generally require companies to be bonded, provide clear written contracts, and offer a “right to cancel” period (usually three business days). Working with a local company ensures they are compliant with Indiana’s specific registration and bonding requirements.
Can a local company remove accurate negative information?
No reputable company can—or should—claim they can remove accurate, verifiable, and timely negative information. If you actually missed a payment two months ago and the bank reported it correctly, that item is legally allowed to stay on your report for seven years. However, we often find that “accurate” items are actually reported incorrectly—perhaps the date is wrong, the amount is slightly off, or the account was sold to a collector who didn’t update the status. In those cases, the item can be challenged and potentially removed.
Conclusion
A low credit score isn’t a life sentence; it’s just a hurdle. Whether you’re in Crown Point or anywhere in Northwest Indiana, finding the best local credit repair is about finding a partner who values your financial health as much as you do.
At United Credit Experts, our mission is financial empowerment. We don’t just want to see your numbers go up; we want you to understand the “why” behind those numbers. By simplifying credit basics and providing expert consulting, we help you build a foundation for a lifetime of financial success.
Don’t let errors or past mistakes dictate your future. Take the first step toward your financial comeback today.