
Your Credit Score Is Costing You More Than You Think

If you’re looking for a professional credit fixer near you, here are the top options to get your credit back on track fast:
Top Ways to Find Professional Credit Repair Help:
- Full-service credit repair companies – Dispute errors, intervene with creditors, and monitor your score (e.g., United Credit Experts)
- Credit repair attorneys – Handle complex cases like identity theft using consumer protection laws
- Nonprofit credit counselors – Low-cost help with budgeting, debt management, and credit basics
- Local credit consultants – One-on-one personalized service in your area
A bad credit score doesn’t just block loans. It can mean higher insurance rates, rejected rental applications, and even fewer job opportunities. For many people, it feels like being stuck in a financial trap with no way out.
The frustrating part? A lot of credit damage comes from errors on your report – mistakes you didn’t even cause. Studies show credit report errors are far more common than most people realize. And those errors can quietly drag your score down for years.
That’s where a professional credit fixer comes in.
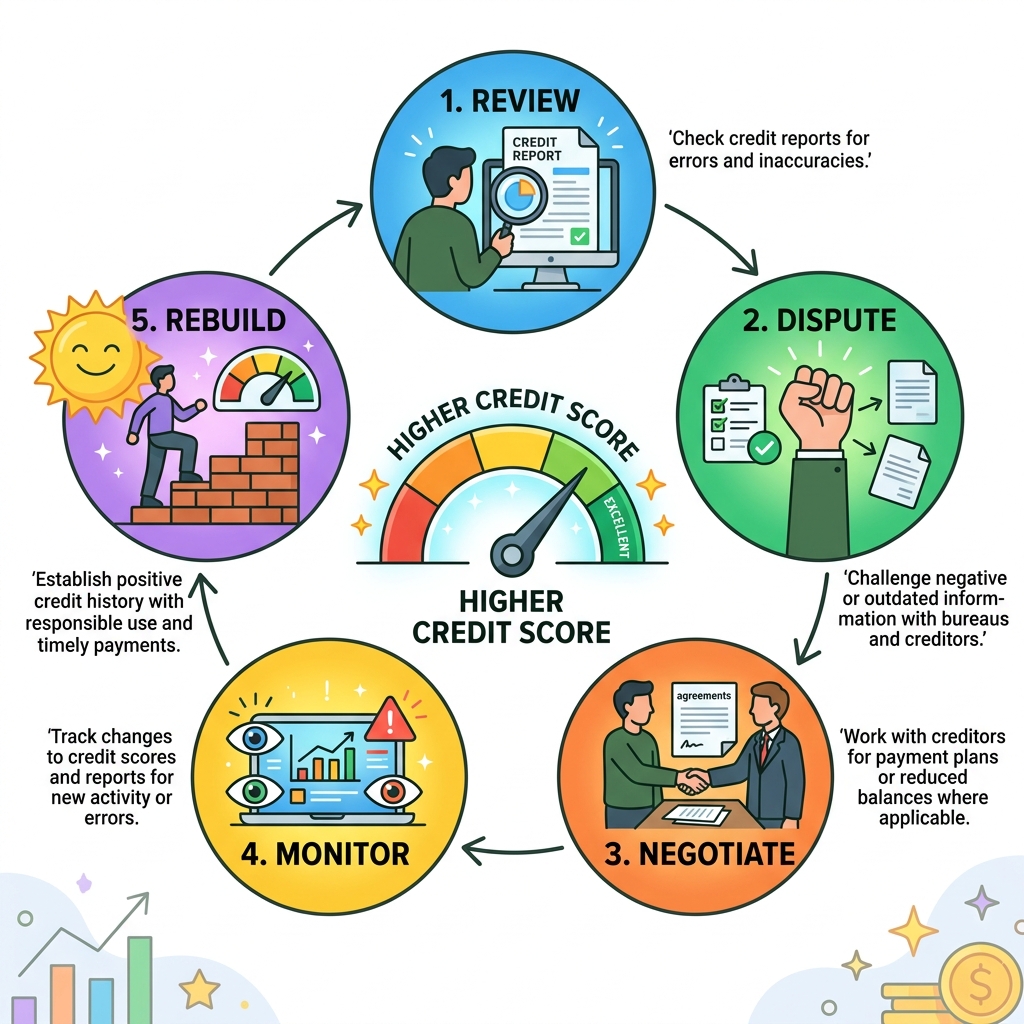
A qualified credit repair professional can review your full credit history, identify inaccurate or unverifiable items, and dispute them on your behalf. They know the system, the timelines, and the laws that protect you.
This guide breaks down exactly what to look for, what to avoid, and how to choose the right professional credit repair service near you.
Why You Should Hire a Professional Credit Fixer Near You
When you realize your credit score is in the basement, the first question is usually: “Can I do this myself, or should I hire someone?” It is a bit like fixing a car. You could watch a dozen videos and try to take the engine apart in your driveway, but if you want it done right the first time without losing your mind, you call a mechanic.
DIY vs Professional
The DIY route is technically “free,” but it comes with a massive “time tax.” To fix your own credit, you have to pull reports from all three bureaus, identify every single error, draft formal dispute letters, mail them out, and then track the 30-day response window for each one. If a bureau rejects your dispute (which they often do on the first try), you have to know how to follow up with the right legal jargon to make them take you seriously.
Hiring a professional credit fixer near you—especially in areas like Crown Point or Northwest Indiana—means you are hiring an advocate. We understand the credit repair process from start to finish. Professionals bring a level of persistence and systematic follow-up that most busy people simply can’t maintain. We don’t just send a letter and hope for the best; we manage the entire lifecycle of the dispute.
Time Management and Bureau Timelines
Time is of the essence, especially if you are looking at 8 steps to buying your dream house. Under the Fair Credit Reporting Act (FCRA), credit bureaus must investigate disputes within 30 days. However, if you provide additional information during that window, they can extend it to 45 days.
A professional ensures that your disputes are “clean” and backed by the right documentation the first time, preventing unnecessary delays. When you’re trying to qualify for a mortgage or a car loan, every 30-day cycle matters. A pro keeps the gears turning while you focus on your life and your job.
Services Offered by a Professional Credit Fixer Near Me
What exactly does a “fixer” do? It’s more than just erasing bad marks. It’s about a comprehensive strategy to restore your financial integrity.
- Customized Dispute Letters: We don’t use “cookie-cutter” templates that credit bureaus have programmed their computers to ignore. We craft specific challenges based on the laws governing reporting accuracy.
- Creditor Intervention: Sometimes the issue isn’t with the bureau, but with the original creditor. We can communicate directly with banks or medical offices to verify the data they are sending to the bureaus.
- Collections Management: Dealing with debt collectors is stressful. We help you understand collections and credit scores and how to handle these items so they stop dragging your number down.
- Identity Theft Recovery: If your identity was stolen, you need more than a simple dispute. We can help implement IdentityTheft.gov recovery plans to ensure fraudulent accounts are permanently removed and your identity is protected moving forward.
- Account Recovery and Debt Resolution: For those in Indiana dealing with old utility bills or medical debt, a professional can help navigate the path to resolving these accounts so they no longer haunt your report.
How to Vet a Professional Credit Fixer Near Me
Unfortunately, the credit repair industry has its share of “bad actors.” You want a partner, not a predator. Here is how to tell the difference.
Red Flags to Watch For:
- Demanding Upfront Payment: This is a huge no-no. Federal law (CROA) prohibits credit repair companies from charging you before they have fully performed the promised services.
- Guaranteed Results: No one can “guarantee” a specific score increase or the removal of accurate information. If they promise you an 800 score by next Tuesday, run the other way.
- Advising Dishonesty: If a company tells you to create a “new” credit identity using an EIN or suggests you lie on a loan application, they are asking you to commit fraud.
- Discouraging DIY: A legitimate company will be honest and tell you that you can do this yourself, but they offer a service that saves you time and provides expertise.
To recognize and avoid scams, always check for transparency. A reputable professional credit fixer near you will provide a written contract, explain your legal rights, and offer customizable reporting so you can see exactly what is happening with your file at any time.
Understanding the Costs of Credit Consulting
Let’s talk numbers. Hiring a professional is an investment, but it’s important to understand what you’re paying for. Most reputable services follow a subscription or “per-deletion” model.
Setup Fees and Monthly Charges
Typically, you will see a “first work fee” or setup fee. This usually covers the initial deep dive into your credit reports, the creation of your case file, and the first round of disputes. After that, most companies charge a monthly service fee.
According to industry data, the average cost of credit repair services generally falls into these ranges:
- Setup/First Work Fees: $99 – $195
- Monthly Subscription: $20 – $150
While this might seem like an extra expense, you have to weigh it against what bad credit costs. A person with a 620 score might pay $200 more per month on a mortgage than someone with a 740 score. Over a year, that’s $2,400 wasted on interest. In that context, a few months of professional consulting pays for itself many times over.
| Feature | DIY Credit Repair | Professional Credit Fixer |
|---|---|---|
| Cost | $0 (plus postage/supplies) | $100 – $150/mo |
| Time Investment | 10-20 hours per month | 1-2 hours (initial setup) |
| Expertise | Learning as you go | Years of industry experience |
| Success Rate | Variable (prone to rejection) | Higher (due to systematic follow-up) |
| Stress Level | High | Low |
Legal Protections and Realistic Expectations
You aren’t just at the mercy of the credit bureaus; you have powerful federal laws on your side. Any professional credit fixer near you must abide by these rules, or they aren’t worth your time.
The Credit Repair Organizations Act (CROA)
This is the “Bill of Rights” for credit repair consumers. Under CROA protections, companies:
- Cannot charge you until services are performed.
- Must provide a written contract.
- Must inform you that you can repair your own credit for free.
- Must allow you a 3-day right to cancel the contract without any penalty.
The Fair Credit Reporting Act (FCRA)
The FCRA is the law that forces credit bureaus to be accurate. It gives you the right to know your rights under FCRA, which includes the right to dispute inaccurate, incomplete, or unverifiable information. If a bureau cannot prove that a negative item is 100% accurate, they are legally required to remove it.
Setting Realistic Expectations
A professional credit fixer is a consultant, not a magician. Here is what you can realistically expect:
- Results take time: You won’t see a jump overnight. It usually takes at least two or three cycles of disputes to see significant movement.
- Accurate info stays: If you really did miss three car payments last year and the bank has the records to prove it, that information is likely staying on your report.
- Total financial health: Repairing the past is only half the battle. You also need to focus on what affects a credit score today, like keeping your credit utilization low (under 30%) and paying every bill on time moving forward.
How Long Does Credit Restoration Take?
The most common question we get in Indiana is, “How long until I can buy my house?”
Generally, you should expect a 60-90 day window to see the first tangible results. This isn’t because the credit fixer is slow; it’s because of how the system is built.
- Month 1: Your consultant reviews your reports and sends the first round of disputes.
- 30-45 Days Later: The credit bureaus investigate and mail back their results.
- Month 2: Your consultant reviews those results. Items might be deleted, or the bureau might ask for more proof. A second round of “rebuttal” letters is sent.
- Month 3: The second round of results comes in, and the updated scores start to reflect the changes.
While this process is happening, you can monitor your progress using AnnualCreditReport.com for free weekly reports. This allows you to see deletions in real-time as the bureaus update their records.
Frequently Asked Questions about Credit Repair
We know you have questions. At United Credit Experts, we believe in the ABCs of Credit—starting with the basics so you feel empowered.
Can I repair my credit for free on your own?
Yes, absolutely. Federal law entitles you to a free credit report from each of the three major bureaus (Equifax, Experian, and TransUnion) every week through 2026 via AnnualCreditReport.com. You can write your own dispute letters and mail them yourself.
The reason people hire a professional credit fixer near them is the same reason people hire a tax professional: expertise and time. If you have a complex report with dozens of errors, identity theft issues, or aggressive debt collectors, the DIY route can become a full-time job. We simplify the basics—defining credit simply as “lent money you repay later”—and handle the heavy lifting of the bureaucracy for you.
What items cannot be removed from a credit report?
Legally, no one can remove accurate, verifiable, and timely negative information.
- The 7-Year Rule: Most negative items (late payments, collections, foreclosures) stay on your report for 7 years from the date of the first delinquency.
- Bankruptcy: Chapter 7 bankruptcy can stay for 10 years.
- Accurate Data: If the information is true and the creditor can prove it, it stays.
However, many items on credit reports are not accurate. They might have the wrong date, the wrong amount, or belong to someone with a similar name. These are the items we target. For more details, check out our FAQs.
Should I use a professional for identity theft?
Yes. Identity theft is a unique beast. It’s not just a “mistake”; it’s a crime. When someone steals your identity, they can open dozens of accounts in your name, leaving you with a mountain of fraudulent debt.
A professional can help you navigate the IdentityTheft.gov process, which involves filing affidavits and police reports. We can provide the legal intervention and personalized recovery plans needed to block these fraudulent charges from your report permanently. This often requires a level of persistence that goes beyond standard credit repair.
Conclusion
Your credit score is the heartbeat of your financial life. It determines where you live, what you drive, and how much you pay for the privilege. If your score is being dragged down by errors, old accounts, or the aftermath of identity theft, you don’t have to face the credit bureaus alone.
At United Credit Experts, we provide the credit education and consulting services you need to regain your financial integrity. We serve neighbors across Northwest Indiana and Crown Point, helping them understand the “credit game” and how to win it. We believe in simplifying the complex so you can move forward with confidence.
Don’t let a three-digit number stand between you and your goals. Whether you’re looking for a professional credit fixer near you to handle the hard work or just need some guidance on the basics, we’re here to help.
Ready to take the first step toward a better score? Get Started with our team today and let’s get your credit in shape together.