
Your Credit Score Is Costing You Money in Cincinnati
If you’re looking for a cincinnati credit fix service, United Credit Experts provides a comprehensive approach to credit repair in 2026. Although our headquarters are in Northwest Indiana, we specialize in helping residents across the Tri-State area, including Cincinnati, navigate the complexities of credit reporting with personalized consulting and a proven dispute process.
Poor credit doesn’t just hurt your pride. It hits your wallet — hard.
In Cincinnati, a low credit score can mean getting turned down for an apartment, paying higher car insurance premiums, or being denied a home loan entirely. And once you’re stuck in that cycle, it’s tough to break out.
Here’s a sobering fact: 34% of consumers have found at least one error on their credit report. That means roughly one in three people may be paying the price for a mistake they didn’t even make.
The good news? You have options. Whether you’re dealing with collections, late payments, or a score that just won’t budge, a qualified credit fix service serving Cincinnati can help you challenge inaccurate information, build better habits, and open doors that felt permanently closed.
This guide breaks down how to improve your credit, what to watch out for, and how to get started — so you can make the right call for your situation.
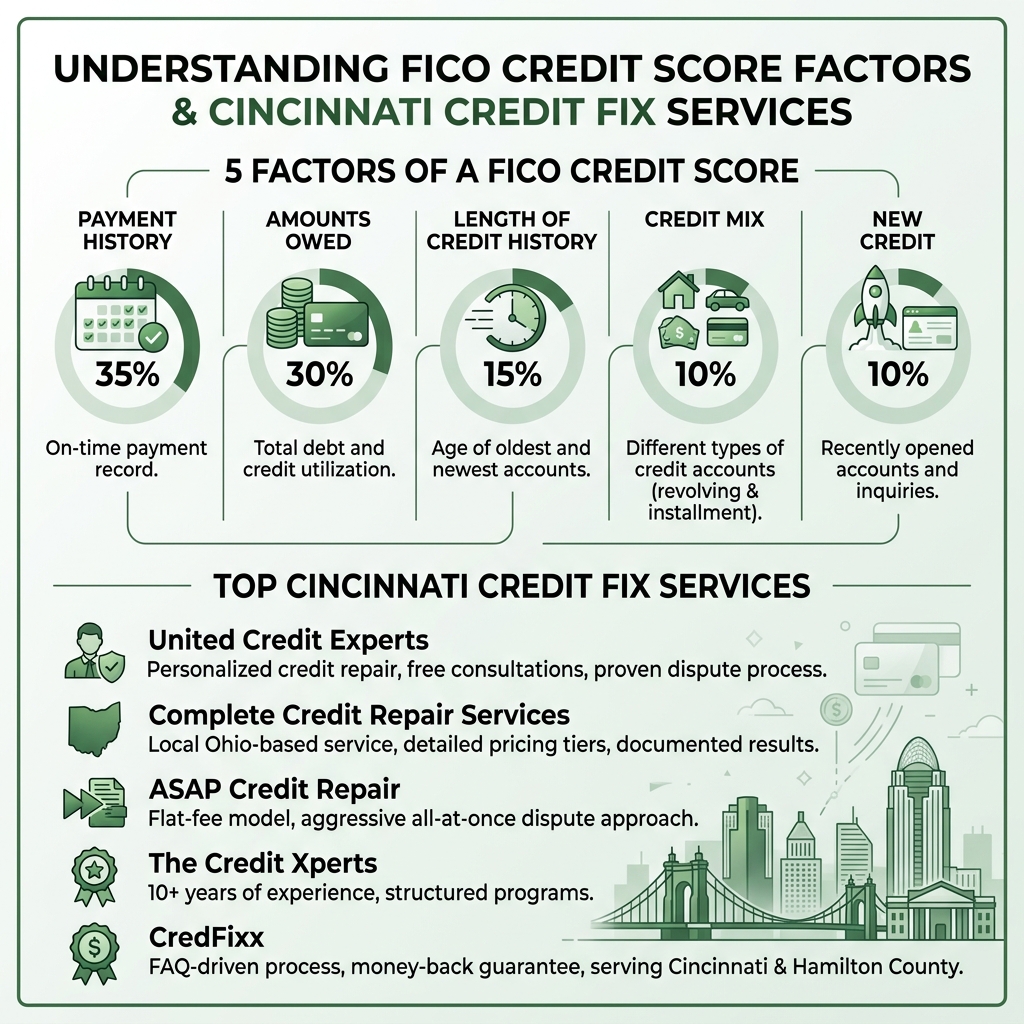
Why Credit Health is a Lifeline for Cincinnati Residents
In the Queen City, your credit score is much more than a three-digit number; it is a financial lifeline. Whether you are strolling through Over-the-Rhine or looking for a quiet spot in Hyde Park, your credit follows you. At United Credit Experts, we serve the Cincinnati region by keeping things simple: credit is essentially money lent to you today that you promise to pay back later. How well you’ve kept that promise in the past determines your “score.”
For Cincinnati residents, this score dictates the quality of your life in several ways:
- Housing Access: Landlords across Hamilton County use credit checks to approve leases. A low score might not just get you a “no,” but it could also result in a much higher security deposit.
- Loan Approvals: Dreaming of a home near the Bengals’ stadium? Most conventional loans require at least a 620 score. Without it, your mortgage application might hit a brick wall.
- Utility Activation: Duke Energy and other utility providers often check your credit before turning on the lights. If your score is low, you might be hit with a hefty upfront deposit.
- Insurance Premiums: Did you know that in Ohio, auto insurers can use credit-based insurance scores to set your rates? While it can’t be the only factor, a poor score often leads to higher monthly bills.
- Employment Screening: Many employers in Cincinnati’s growing healthcare and logistics sectors perform credit checks as part of their background screening, especially for roles involving financial responsibility.
Improving your score through a cincinnati credit fix service isn’t just about vanity—it’s about economic empowerment. Even though our physical offices are located in Northwest Indiana, we are proud to provide expert consulting to our neighbors in Cincinnati. You can learn more about these fundamentals in our guide to the ABCs of credit.
Understanding Your Rights and the Dispute Process
When you decide to fix your credit, you aren’t just asking for a favor; you are exercising your legal rights. The Fair Credit Reporting Act (FCRA) is a federal law that ensures your credit report is accurate, private, and verifiable. If information on your report is wrong, the bureaus are legally obligated to fix it.
In Ohio, you are also protected by the Ohio Attorney General’s consumer protection section. If a company treats you unfairly, you have a place to turn.
The standard dispute process generally follows these steps:
- Identify Errors: Pull your reports from AnnualCreditReport.com.
- Gather Evidence: Find receipts, bank statements, or court records that prove the error.
- Draft a Letter: Use a CFPB sample dispute letter to clearly state what is wrong.
- Send via Certified Mail: This provides a paper trail and proof of receipt.
- Wait 30 Days: The credit bureaus typically have 30 days to investigate and respond.
Knowing your rights under the FCRA is the first step toward financial freedom. It’s also important to understand how checking your credit affects your score:
| Feature | Soft Credit Inquiry | Hard Credit Inquiry |
|---|---|---|
| Occurrence | Personal checks, employer checks, pre-approvals | Mortgage, auto, or credit card applications |
| Score Impact | None | Typically 2–5 points |
| Visibility | Only you can see them | Potential lenders can see them |
| Duration | Varies | Stays on report for 2 years |
How a Cincinnati Credit Fix Service Addresses Negative Items
A professional cincinnati credit fix service doesn’t just “delete” things; they hold creditors and bureaus accountable. Some common items they address include:
- Late Payments: Even one 30-day late payment can cause a significant score drop.
- Collections: These can haunt your report for years. We provide deep insights into how collections affect credit scores.
- Medical Debt: Rules have recently changed! Under the Medical Debt Relief Act of 2022, paid medical bills under $500 are no longer reported. You can read more on medical debt removal rules via the CFPB.
- Identity Theft: If someone used your name to open accounts, a service can help you navigate the complex recovery process.
- Public Records: This includes bankruptcies and foreclosures, which require specific legal expertise to challenge if they are reported incorrectly.
Choosing the Right Cincinnati Credit Fix Service for Your Financial Goals
Choosing a company to handle your financial future is a big deal. You want a partner, not a predator. Here is what we recommend looking for:
- Compliance: Ensure they follow the Credit Repair Organizations Act (CROA). This means they cannot charge you upfront fees before work is performed.
- Transparency: They should provide a written contract detailing your three-day right to cancel and a clear list of all costs.
- No “Magic” Promises: If a company claims they can remove 100% accurate negative items, run the other way. Legitimate services focus on inaccuracies and unverified data.
- Reputation: Check the Ohio Attorney General’s complaint database for any red flags regarding the company.
At United Credit Experts, we believe in empowering you through education. We don’t just “fix” things; we consult with you so you understand the why behind the what.
The Cost of a Professional Cincinnati Credit Fix Service
Pricing for a cincinnati credit fix service can vary as much as the weather in the Ohio Valley. Generally, you’ll see three models:
- Monthly Subscriptions: These usually range from $65 to $149 per month. This is common for ongoing dispute work and monitoring.
- Flat-Fee Models: Some companies charge a one-time fee (often around $499) to handle a specific number of items all at once.
- Onboarding Fees: Many firms charge a small initial fee (typically $60–$100) to pull your reports and conduct a professional analysis.
While the DIY route is free, many Cincinnati residents find that a professional analysis saves time and catches errors they might have missed. A pro can help with “escalated disputes”—the ones where the credit bureau digs their heels in and refuses to budge.
Proven Strategies for Building and Maintaining Positive Credit
Repairing the past is only half the battle; you also have to build the future. Here are the strategies we recommend to our neighbors in Cincinnati:
- Automate Everything: Payment history is 35% of your score. Setting up auto-pay ensures you never miss a deadline.
- Watch Your Utilization: Keep your balances below 30% of your limits. If you have a $1,000 limit, try not to owe more than $300. You can learn more about what affects a credit score to master these ratios.
- Use Credit-Builder Loans: Local Cincinnati credit unions often offer these. You “borrow” a small amount that sits in a savings account while you make payments, which are reported to the bureaus.
- Authorized Users: If a family member has a long, perfect credit history, being added as an authorized user can give your score a “piggyback” boost.
- Free Local Resources: The Cincinnati Financial Empowerment Center offers free, high-quality advice for residents looking to stabilize their finances.
For more deep dives, the educational resources from the CFPB are an excellent place to start.
Frequently Asked Questions about Credit Repair in Ohio
How long does it take to see results from a Cincinnati credit fix service?
Credit repair is a marathon, not a sprint. While some clients see a 10–20 point bump within the first 35 days due to quick removals, most significant changes happen in the 60-to-90-day window.
For complex cases involving bankruptcies or identity theft, the process can take six months to a year. It’s important to remember the seven-year reporting limit; most negative items must fall off after seven years (ten for some bankruptcies), regardless of whether you hire a service.
Can negative items reappear on my credit report after being removed?
It is rare, but it can happen. If a creditor “re-verifies” the information, the bureau may put it back. However, under the Fair Credit Reporting Act, the bureau must notify you in writing within five days if they re-insert a deleted item. A reputable cincinnati credit fix service will monitor your reports to ensure that once something is gone, it stays gone.
Does removing a debt from my report eliminate my obligation to pay it?
No. This is a common misconception! Removing a collection account from your credit report means it no longer hurts your score, but you still legally owe the money. The creditor can still sue you or attempt to garnish wages if the debt is within the Ohio statute of limitations.
To protect yourself from aggressive collectors, you should familiarize yourself with the Fair Debt Collection Practices Act (FDCPA). If a debt is truly yours, we often suggest debt validation—forcing the collector to prove they have the legal right to collect that specific amount.
Conclusion
At United Credit Experts, our mission is simple: we want to take the mystery out of your money. By simplifying credit basics and providing expert consulting, we empower Cincinnati residents to take control of their financial destinies. Although we are based in Northwest Indiana, our commitment to financial literacy extends to the entire Cincinnati community.
Whether you choose a professional cincinnati credit fix service or decide to tackle the bureaus yourself, the most important step is the first one. Don’t let a mistake from three years ago stop you from buying a home today.
Ready to see what’s possible? Start your credit improvement process with us today. We’re here to help you navigate the road to a better score, one step at a time.