
Your Credit Score Is Costing You More Than You Think
Finding an affordable credit dispute service doesn’t have to mean settling for less — here are the best options at a glance:
| Service Type | Typical Monthly Cost | Best For |
|---|---|---|
| Full-service credit repair | $50–$150/month | Multiple errors, complex disputes |
| Pay-per-delete | $50–$150 per item | Few errors (under 5 items) |
| AI-powered DIY tools | $25–$50/month | Tech-savvy, hands-on users |
| Free DIY (self-managed) | $0 | Simple, single-bureau errors |
Credit report errors are far more common than most people realize. And every mistake sitting on your report — a misreported late payment, a wrong account status, an account that isn’t even yours — can mean higher interest rates, loan denials, and doors that simply won’t open.
If you’ve been turned down for a home loan or stuck paying sky-high rates on a car loan, your credit report may be part of the problem.
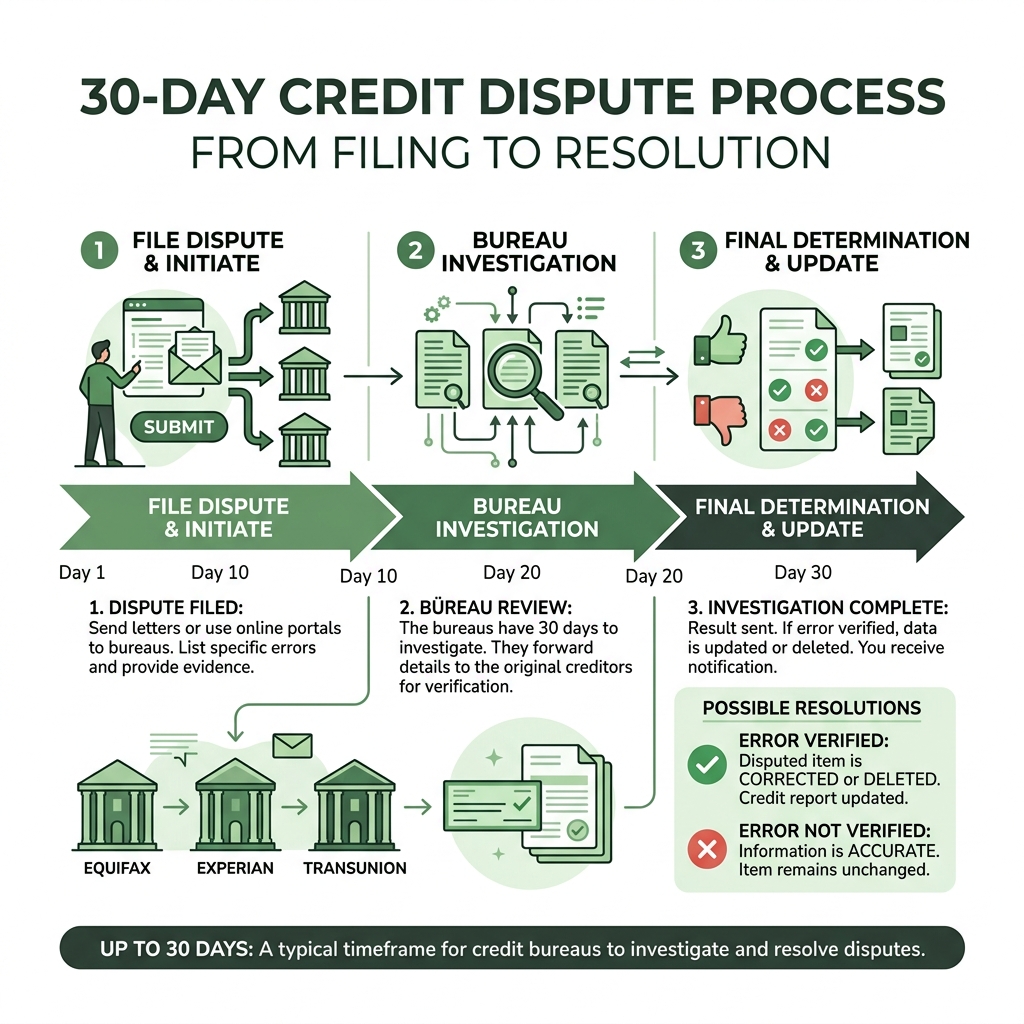
The good news? You have legal rights. Under the Fair Credit Reporting Act (FCRA), credit bureaus must investigate disputes within 30 days. That means errors can — and should — be challenged.
The tricky part is knowing which services are actually worth paying for, which ones are scams, and when you can just handle it yourself for free.
This guide breaks it all down.
Choosing an Affordable Credit Dispute Service That Works
When we talk about credit at United Credit Experts, we like to keep it simple: credit is just lent money that you agree to repay later. But when that repayment history is recorded incorrectly, it creates a “bad credit” profile that follows you everywhere. Choosing an affordable credit dispute service is about finding a partner to help you correct those records without draining your savings.
In Northwest Indiana and across Indiana USA, we see many neighbors struggling with “zombie debt” or errors from old medical bills. Finding a service that works means looking past the flashy marketing and into the fine print of the contract.
Defining Affordability in Credit Repair
To us, “affordable” doesn’t just mean the lowest price tag. It means value. A service that charges $50 a month but does nothing is more expensive than a service that charges $100 and actually gets results. True affordability involves:
- Transparent Pricing: No surprise fees for “extra” disputes.
- Budget Alignment: Matching the service to your specific needs (e.g., if you only have one error, don’t pay for a massive monthly subscription).
- Price-Matching: Some top-tier companies will match a competitor’s lower rate if you ask.
Understanding What Bad Credit Costs is essential here. If a higher score saves you $200 a month on a mortgage, spending $100 a month for a few months to fix your report is a fantastic investment.
Typical Cost Structures and Fees
Most companies in the industry follow a few standard pricing models. You should expect to see:
- Setup Fees: Often called “First Work Fees,” these range from $19 to $200. Under the law, companies cannot charge you before they have actually performed work.
- Monthly Subscriptions: The industry average is between $50 and $150 per month.
- Hidden Charges: Watch out for “per-bureau” fees or extra costs for pulling your credit reports.
According to our FAQs, you should always have a clear understanding of your cancellation rights. Most reputable services allow you to cancel at any time without a penalty, as required by the Credit Repair Organizations Act (CROA).
How Credit Dispute Services Improve Your Financial Health
The primary goal of any affordable credit dispute service is to ensure your credit report is an accurate reflection of your financial behavior. There are three major players that hold your data: Equifax, Experian, and TransUnion. If one of them has a mistake, your score will suffer.
The Mechanics of a Credit Dispute
The process is a legal tug-of-war. When you or a service identifies an error, a formal dispute is sent to the bureau. The bureau then has 30 days (sometimes 45 if you provided additional info) to investigate. They must contact the “furnisher” (the bank or collection agency that reported the info) to verify it. If the furnisher can’t prove the debt is accurate and yours, the bureau must remove it.
You can learn more about how the bureaus operate in our Credit Bureaus section. For our friends in the region, checking specific Frequently Asked Questions – TransUnion Canada can provide insights into how international bureaus handle similar data, though US laws like the FCRA are your primary protection here in Indiana.
Our team follows a strict Our Process to ensure every dispute is backed by the right legal language to get the bureau’s attention.
Expected Results and Score Improvements
Don’t expect overnight miracles. Credit repair is a marathon, not a sprint.
- The 90-Day Window: Most consumers begin to see tangible results and score changes within 3 to 6 months.
- Point Gains: While every situation is unique, research shows that many customers see a 15-40 point increase after 90 days. Some more intensive services report average increases of 40–100 points over a longer period.
If you are looking for the Best Way to Bring Up Credit Score Quickly, disputing errors is often the fastest “hack” because it removes negative weight rather than just adding positive weight.
Comparing Payment Models for an Affordable Credit Dispute Service
Choosing the right payment model can save you hundreds of dollars.
| Model | Average Cost | Pros | Cons |
|---|---|---|---|
| Monthly Subscription | $79 – $129 | Unlimited disputes, better for many errors | Can get expensive if it takes 6+ months |
| Pay-Per-Delete | $50 – $150 per item | You only pay for results | High cost if you have 10+ errors |
| Flat-Rate / One-Time | $500 – $1,000 | Predictable total cost | Large upfront commitment |
When to Choose Pay-Per-Delete
This model is perfect if your credit report is mostly clean but has one or two stubborn “ghosts” from the past. For example, if you have one old Collections account that shouldn’t be there, paying a flat $100 for its removal is much cheaper than three months of a subscription service.
The Benefits of Monthly Subscription Plans
If your report looks like a battlefield with dozens of errors, a monthly plan is your best friend. Many professional services often offer unlimited disputes for a flat monthly fee. This is the Fast Track to Financial Freedom for those dealing with identity theft or widespread reporting errors.
For those in Crown Point, IN, local experts offer tailored coaching that often fits into these monthly models.
DIY vs. Professional Help: When to Pay for Credit Repair
We often get asked: “Can’t I just do this myself?” The answer is yes. Legally, you can do everything a credit repair company does.
Saving Money with DIY Methods
If you have the time and organizational skills, DIY is the ultimate affordable credit dispute service.
- Free Reports: You are entitled to one free report from each bureau every week via AnnualCreditReport.com through 2026.
- Direct Disputes: You can use the online portals at Experian, Equifax, and TransUnion to flag errors.
- Resources: We recommend watching Credit Reports with John Oliver for a humorous but accurate look at why these bureaus make so many mistakes and how to spot them.
When Professional Expertise is Cost-Effective
While DIY is free, it’s not always “cheap” when you consider your time. Professional services are worth the money when:
- Complex Errors: You’re dealing with bankruptcies, foreclosures, or identity theft.
- Legal Language: Professionals know the specific verbiage to use to prevent bureaus from dismissing your dispute as “frivolous.”
- Creditor Intervention: Sometimes you need to go straight to the source. A professional service can negotiate with debt collectors under the Fair Debt Collection Practices Act (FDCPA) to have them stop reporting a debt they can’t prove.
Red Flags to Avoid When Searching for an Affordable Credit Dispute Service
The credit repair industry has its fair share of bad actors. In fact, the CFPB recently distributed refund checks to over 4 million victims of illegal telemarketing practices by certain agencies.
Identifying Credit Repair Scams
Be on high alert for these red flags:
- Upfront Fees: If they ask for money before they’ve done any work, run. It’s a violation of the CROA.
- Guaranteed Results: No one can guarantee a score increase or the removal of accurate information.
- New Identities: Any company telling you to apply for an EIN or a “Credit Privacy Number” (CPN) is asking you to commit federal fraud.
- Telling You Not to Contact Bureaus: You always have the right to contact the bureaus yourself.
For a deeper dive into how some debt collection and repair companies operate in the shadows, check out Collection Companies with John Oliver.
Verifying Company Legitimacy
A legitimate affordable credit dispute service will:
- Provide a written contract.
- Explain your legal rights, including your right to cancel within three days.
- Have a physical address (Check out our About Us page to see our commitment to transparency).
- Be honest about what they can’t do (they cannot remove accurate, timely negative info).
Frequently Asked Questions about Credit Disputes
How long does the credit dispute process take?
The bureaus generally have 30 days to investigate. However, the entire process of identifying an error, sending the letter, and receiving a response usually takes 45 to 60 days. If the bureau needs more information, they might get an extra 15 days. You can track our typical timeline in Our Process.
Can a service remove accurate negative information?
No. If you actually missed a payment two months ago and the bank has the records to prove it, that information is legally allowed to stay on your report for seven years. Bankruptcies can stay for ten. A service that claims they can “wipe your slate clean” of accurate debt is lying to you. We focus on What Affects a Credit Score to help you build positive habits while we clear out the errors.
Are credit dispute services legal?
Absolutely. They are governed by the Credit Repair Organizations Act (CROA) and the Fair Debt Collection Practices Act (FDCPA). These laws were designed to protect you, the consumer, from being bullied by large financial institutions or misled by repair companies.
Conclusion
At United Credit Experts, we believe that everyone in Northwest Indiana and beyond deserves a fair shot at financial stability. Credit is simply lent money that you pay back later — it shouldn’t be a source of constant stress because of a clerical error.
Whether you choose a full-service affordable credit dispute service, a local Crown Point expert, or decide to take the DIY route, the most important step is to start. Don’t let your financial future be dictated by a mistake on a piece of paper.
Ready to take the first step toward a cleaner credit report? Get Started with us today and let’s see what we can achieve together.